Stop Chasing Borrowers by Hand
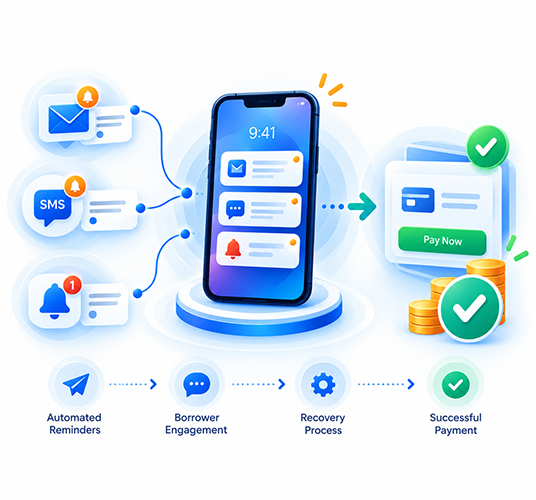
Automate the reminders, trigger recovery workflows, get paid faster — a collection system built for device financing specifically, not a generic debt-collection tool wearing a different logo.
Phone calls. One-off texts somebody remembered to send. A spreadsheet someone updates by hand. All of that, swapped for automated, multi-channel communication that actually keeps borrowers engaged instead of letting cases go cold.
Why Manual Collections Break Down
High staffing cost per case. Follow-ups that show up too late, or don't show up at all. Recovery rates that plateau no matter how much effort gets thrown at them.
The Economics Problem On Small-Ticket Mobile Loans
Communication that's inconsistent enough to actually damage the relationship with the borrower. Almost no visibility into what's working and what isn't. And recovery rates that just plateau, no matter how much effort gets thrown at it.
Recovery rates plateau no matter how much effort gets thrown at the problem — without a structural fix, they stay there.
What Replaces It
Automated reminders across SMS, app, whatever channel fits. Escalation that's rule-based, triggered by actual payment behavior rather than someone remembering to follow up. And a direct line to device locking, for when reminders alone aren't moving the needle.
From First Reminder
to Closed Case
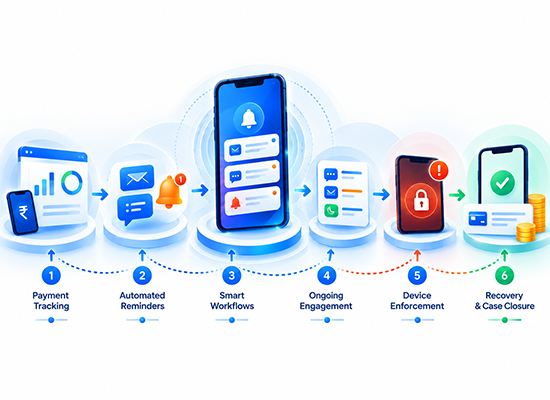
Payment Tracking
Due dates and schedules monitored continuously. Payment events feed the system in real time — rules engine decisions based on current facts, not last night's batch file.
Automated Reminders
Timely, personalized, sent via SMS, push, whatever fits the borrower. Multi-language templates. Goal: cut first-payment miss before enforcement is ever needed.
Smart Workflows
Payment missed, escalation kicks in automatically — your rules, not a guess. Configurable by product, dealer, risk band, and region.
Ongoing Engagement
Consistent, well-timed communication keeps repayment top of mind. Still digital-heavy — humans focus on disputes and hardship cases.
Device Enforcement
When reminders alone aren't moving the needle, device locking kicks in — cheaper and faster than repossession. The same platform, no handoff required.
Recovery and Closure
Cases close automatically once payment's confirmed. No manual sign-off. Late-stage accounts export to agency or legal CRM with full digital history attached.
— Key Features
Core Capabilities
Automated, Multi-Channel Reminders
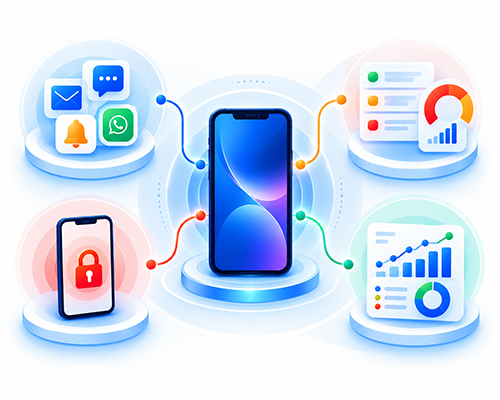
SMS, in-app push, email, configurable automated triggers — all from one platform. Rule-based escalation, triggered by actual payment behavior rather than someone remembering to follow up.
Borrower Segmentation by Risk
Borrowers segmented by risk and by what they owe. High-ticket devices carry longer grace periods; high-risk channels escalate faster. Your rules, not a guess.
Direct Integration With Device Locking
Not bolted on — actually wired in. Digital collection handles the conversation, device locking handles enforcement when the conversation alone isn't getting the payment in.
Analytics and Reporting
Portfolio-level performance tracking. Repayment trend analysis across segments. Early flags on high-risk borrowers. Workflow optimization driven by outcomes, not a guess about what should work.
Business Impact
↑ Rate
Higher recovery with
less manual effort
↓ Cost
Per collection
across the portfolio
Scale
Consistent at volume —
doesn't fall apart
↑ Pay
Better repayment from
timely engagement
Auto
Cases close without
manual sign-off
— USE CASES —
Where Teams Use This
EMI Collections for Device Financing :
Due dates and schedules monitored continuously. Automated reminders go out on time, every time — not when someone gets to it. Escalation kicks in automatically on miss.
BNPL Repayment Follow-Up :
Embed device-native collections into your BNPL flow. Configurable escalation by product SKU, risk band, and co-lender. A device control layer without building it yourself.
Telecom Billing and Contract Recovery :
Automate early-stage recovery on postpaid handset EMI and prepaid affordability bundles at near-zero marginal cost per touch. No manual agent involvement at each step.
Retail Installment Collection :
Offer financing confidently knowing early delinquency is handled digitally — before field agents or legal workflow are ever needed. Cases close automatically once payment's confirmed.
The smart solution for mobile device financing businesses.
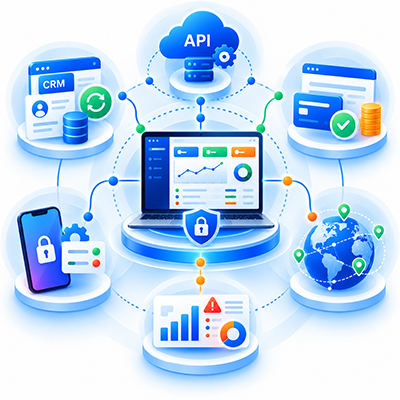
API-based integration with your lending platform. Works alongside your existing CRM and payment systems. Syncs directly with device locking for end-to-end enforcement. Deploys flexibly across geographies — not built around assuming you only operate in one market.
Book DemoTelecom Operators :
Automate early-stage recovery on postpaid handset EMI and prepaid affordability bundles at near-zero marginal cost per touch.
NBFCs & Lenders :
Replace dialler-heavy collections on smartphone books with omnichannel digital recovery — and device enforcement when reminders alone aren't enough.
Fintech Companies :
Embed device-native collections into your BNPL flow — configurable escalation by product SKU, risk band, and co-lender from day one.
Retailers & Distributors :
Offer financing confidently knowing early delinquency is handled digitally — before field agents or legal workflow are ever needed.
PLAYS WELL WITH WHAT YOU ALREADY RUN
Built For Scale, Designed For Control
- API-based integration with your lending platform
- Works alongside your existing CRM and payment systems
- Syncs directly with device locking for end-to-end enforcement
- Deploys flexibly across geographies — not built around assuming you only operate in one market
- Portfolio-level performance tracking and early flags on high-risk borrowers
Frequently Asked Questions
Common questions from collections VPs, NBFCs, and fintechs evaluating digital debt collection.
Modernize How You Collect
Automate every stage of recovery. Collect more. Spend less.