Bring Order to Financed Device Operations
Manage repayments, cut defaults, automate recovery — on a platform built for this specific job, not stitched together out of tools meant for something else.
Gives lenders, telecom operators, and fintech companies control over every stage of a financed device's life. Payment tracking, risk detection, and device enforcement all live in one place.
Why This Needs to Exist
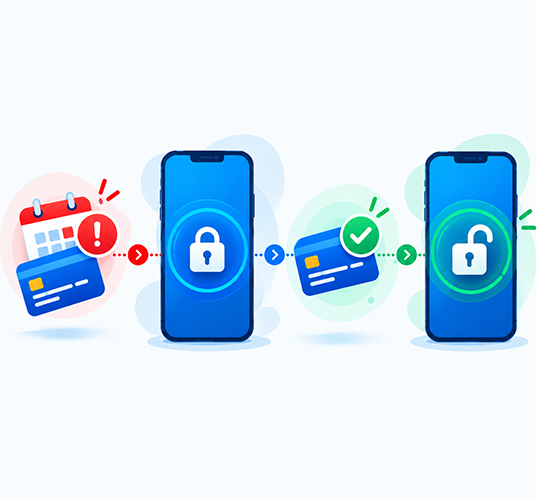
Financing smartphones is good business — but the day-to-day of actually running it is harder than it looks. Default rates chip away at margin quietly. Almost no leverage exists once the device is out the door.
Why Smartphone Portfolios Need a Dedicated Platform
Collections that are slow, manual, and inconsistent from case to case. Fraud you don't catch until it's already cost you. None of that stays isolated — it compounds. Without something structural holding it in check, exposure grows faster than most teams expect.
Without something structural holding it in check, exposure grows faster than most teams expect.
What Control Actually Looks Like
Visibility across the whole lifecycle — enrollment to final payment. Track every device in the portfolio. Watch payments against schedule in real time. Catch risk signals before a default actually happens, not after.
How It Plays Out,
Step by Step
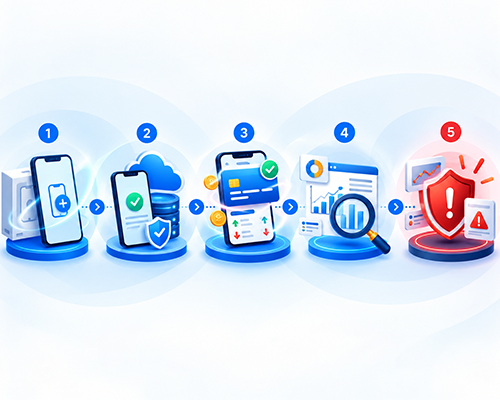
Device Enrollment
Onboard via API or SDK at the point of sale. One IMEI-linked record from checkout to loan closure — duplicate checks prevent ghost assets from inflating your book.
Payment Monitoring
Every scheduled repayment tracked against live payment data. Rules engine decisions based on current facts, not last night's batch file. Reminders cancel automatically when payment clears.
Risk Detection
Borrowers showing early signs of default get flagged before things escalate. Automated, multi-channel reminders before and after due date — with escalating stages before human agents get involved.
Device Control
Remote locking triggers automatically when payments are missed. Graduated restrictions rather than an immediate full brick. Commands queue offline and execute on reconnect.
Recovery & Unlock
Access restores automatically once the account is settled — typically within seconds of payment. Risk scoring and fraud detection baked in throughout the lifecycle.
— Key Features
Core Capabilities
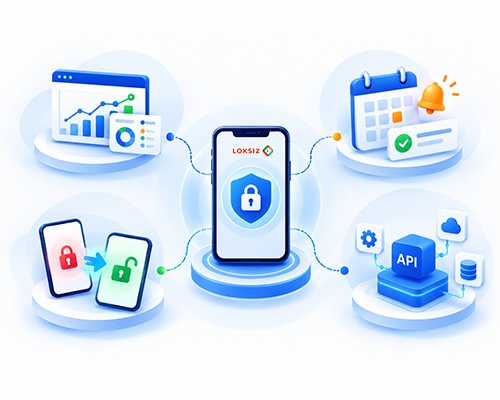
Real-Time Device Monitoring
Every device in the portfolio tracked live — active, delinquent, locked, offline, and closed. Segment by dealer, region, product type, or OEM family.
Automated, Multi-Channel Payment Reminders
Finance reconciliation and digital collections from the same data. Reminders fire across SMS, push, and in-app — and stop automatically when payment clears.
Remote Locking and Unlocking
Automatic, not something a person triggers. Commands queue offline and execute on reconnect. Unlock fires within seconds of payment confirmation.
API-First Integration Layer
REST API and Android SDK built to fit into existing lending and operational stacks. Integration that doesn't mean rebuilding your existing systems first.
What It Means for the Business
40%
Fewer loan defaults —
meaningfully fewer
3x
Better collection
efficiency
99.9%
Lower cost
per recovery
60%
Risk that doesn't scale
with your financing
2s
Unlock fires after
payment clears
— USE CASES —
Where Teams Are Using This
Smartphone Financing Programs :
If a device leaves your hands before it's fully paid for, this is built for that situation — from pilot cohorts of a few hundred devices to national programs.
BNPL Device Products :
A device control layer without building your own OEM relationships. Embed smartphone BNPL in your app without spending months on enforcement infrastructure.
Telecom Contract and Subsidy Programs :
Scale postpaid handset EMI programs or prepaid affordability bundles with built-in risk control — without the default rate scaling right alongside growth.
Retail Installment Sales :
Enroll devices at point of sale via the Android SDK — without a full LMS integration on day one. Sell with installments and stop thinking about the handset the second it leaves the counter.
The smart solution for mobile device financing businesses.
Telecom operators, NBFCs and lenders, fintech companies, retailers and distributors — basically anyone financing handsets. If a device leaves your hands before it's fully paid for, this is built for that situation.
Book DemoTelecom Operators :
Scale device financing programs without the default rate scaling right alongside it. Risk controls in from day one, not bolted on after the first bad quarter.
NBFCs & Lenders :
Lower exposure, push repayment up — without adding to the collections headcount. Reduce credit risk and improve repayment rates across dealer networks.
Fintech Companies :
Bolt on embedded device financing without spending months building the enforcement layer yourselves. A device control layer without building your own OEM relationships.
Retailers & Distributors :
Sell with installments and stop thinking about the handset the second it leaves the counter. Enroll at point of sale via Android SDK — no full LMS integration required on day one.
WHAT SETS IT APART
Built for Global Scale from Day One
End-to-end control across the whole device lifecycle, not just one slice of it. Real-time enforcement, not enforcement-on-a-delay. Integration that doesn't mean rebuilding your existing systems first. Secure, compliant, fully auditable — the boring stuff that actually matters when someone asks for it.
- End-to-end control across the whole device lifecycle, not just one slice
- Real-time enforcement — not enforcement-on-a-delay
- Integration that doesn't mean rebuilding your existing stack first
- Built for global scale from day one
- Secure, compliant, fully auditable — the boring stuff that matters when someone asks for it
Integration Path & Time To Pilot
Engineering teams familiar with REST APIs and webhooks generally complete sandbox integration within two weeks. Focused pilots move in weeks, not months.
From Sandbox Credentials To Production
A pragmatic path that delivers early value without waiting for full program sign-off.
Production depends on LMS complexity, OEM validation, and compliance sign-off — but focused pilots move in weeks, not months.
Outcomes DFRM Programs Measure
Pilots compare a baseline book cohort against a post-enforcement cohort. Outcomes vary by segment, OEM mix, and quality of borrower disclosure at point of sale.
— EXPLORE MORE —
Related Solutions
Device Locking Solution
Graduated remote lock and unlock tied directly to your EMI schedule and DPD threshold. Money stops, phone stops — automatic, not something a person triggers.
Digital Debt Collection
Reminders and escalation that run themselves — so nobody's manually dialing through a spreadsheet. Digital-first before human agents ever get involved.
Reduce Loan Defaults
End-to-end IMEI-linked records, real-time payment event tracking, and fraud prevention signals — fewer defaults, meaningfully fewer, not a rounding error.
API Integration
REST API and Android SDK built to fit into your existing LMS, payment gateways, and POS systems — integration that takes days, not a quarter.
Frequently Asked Questions
Common questions from NBFCs, telecoms, fintechs, and retailers evaluating DFRM.
Start Managing Device Financing Risk With Confidence
Cut defaults, lift recovery rates, and build a financing operation that scales — without losing sleep over what happens after the device leaves your hands.